When investing in several currencies, one can face currency risks. The below example illustrates the concept. The numbers have been chosen to make the example easily understandable. The code can be found in the notebook.
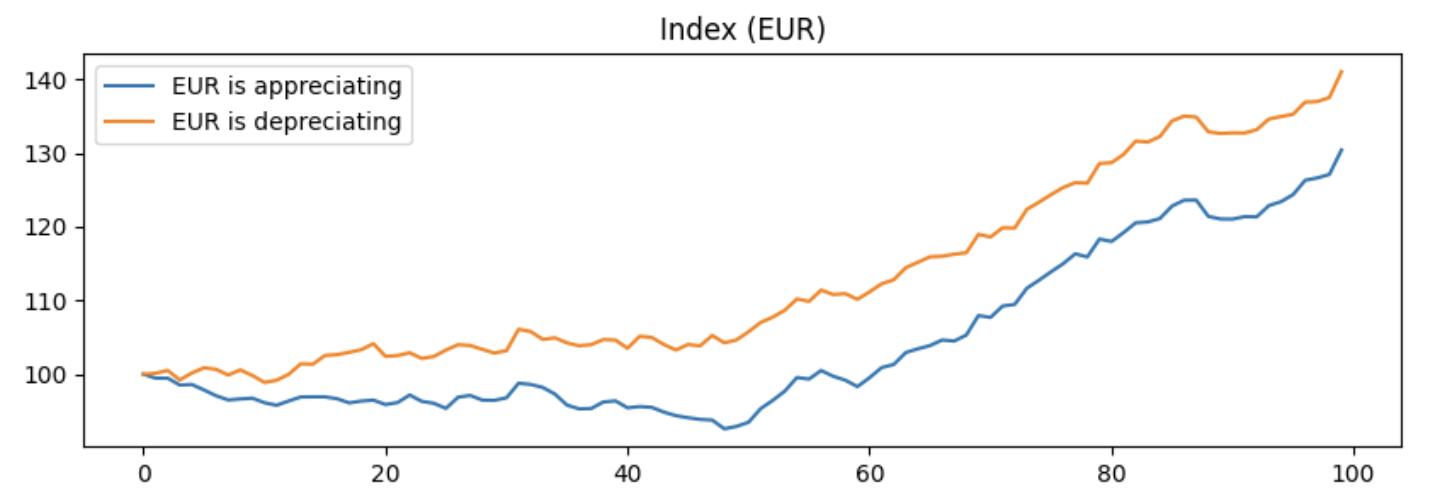
Let’s assume a portfolio is composed of 50% Peugeot (EUR) and 50% Roche (CHF). The reference currency is EUR, meaning that the performance is reported in EUR.
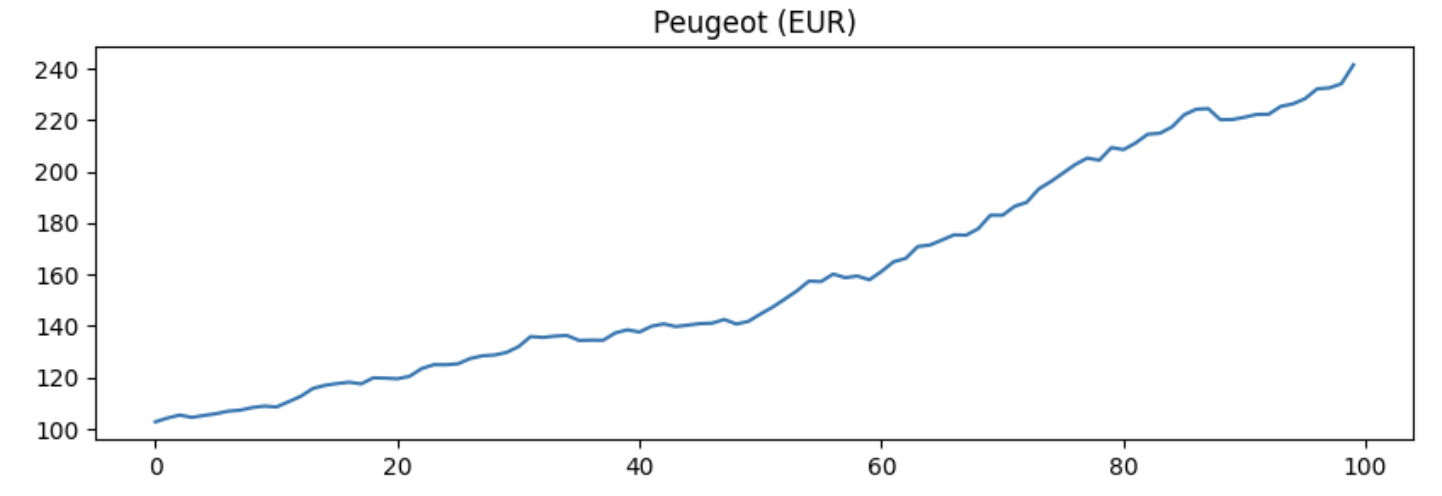
Let’s create a synthetical stock for Peugeot (EUR).
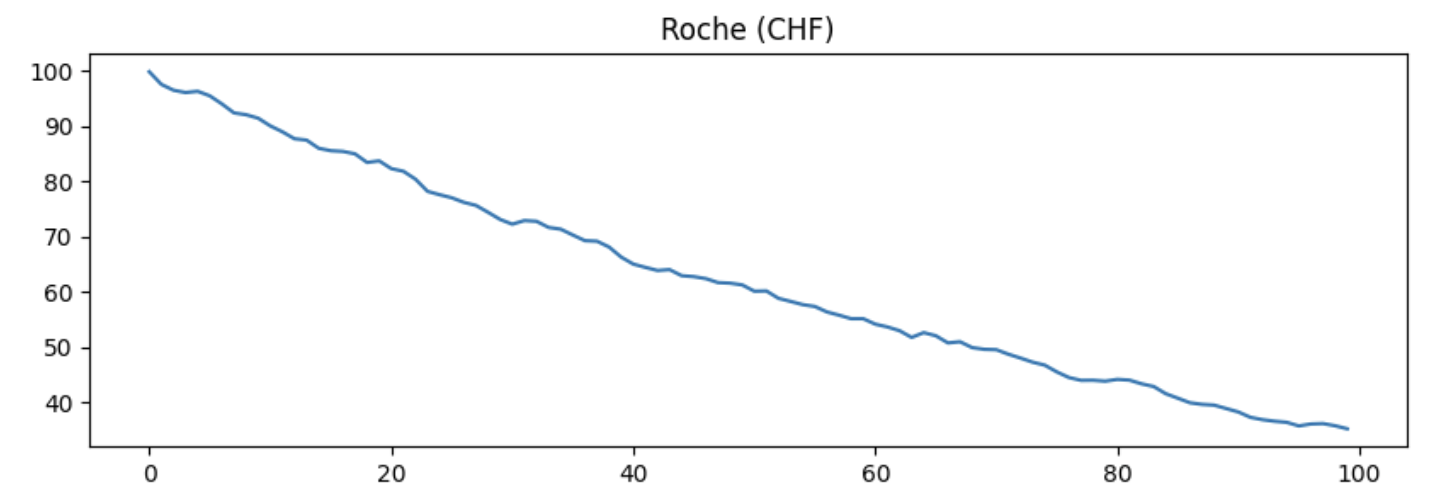
Similarly, we create a synthetical stock for Roche (CHF).
We simulate EURCHF with 2 situations:
-
case 1: EUR is appreciating against CHF
-
case 2: EUR is depreciating against CHF
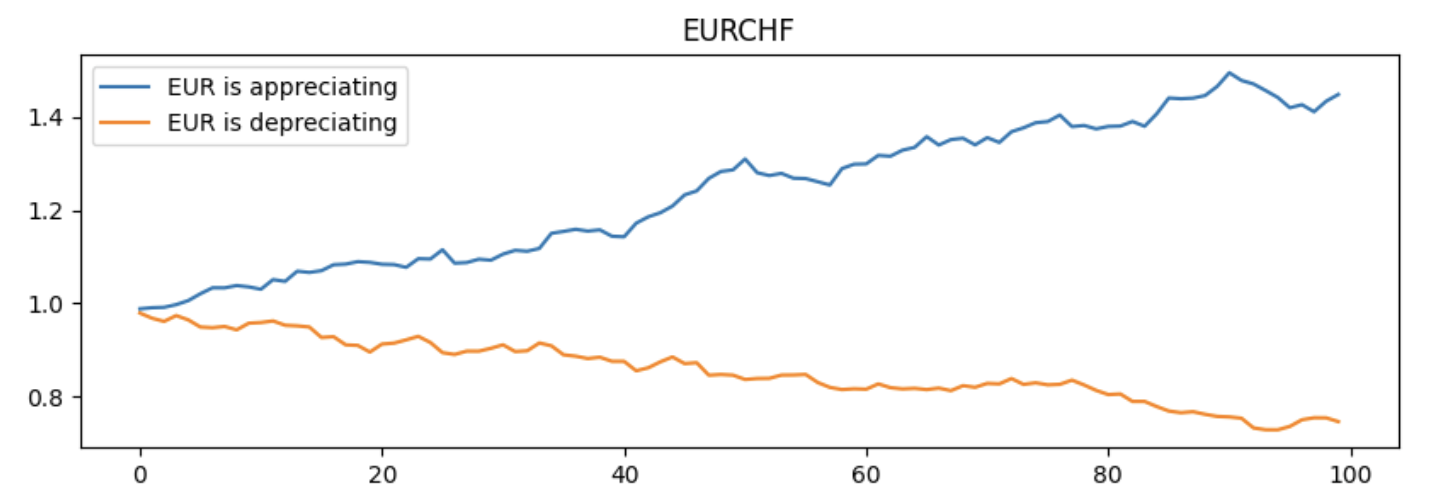
To report the performance in EUR, we need to convert the CHF stock in EUR. Hence, when the EUR is depreciating (CHF is appreciating), we earn more thanks to the CHF stock increase. Consequently, the performance of our portfolio is higher when the CHF is appreciating.
Hedging
Holding assets in a foreign currency is thus a good strategy if we think such currency will remain stable or appreciate over time. If an investor wants only to enjoy the stock appreciation and has no view on the foreign currency, it may be good to consider FX hedging. One possibility is to purchase a FX forward so that at maturity we convert the Roche stock in EUR using a fixed rate. That way, if the CHF decreases (resp. increases), we don’t earn less (resp. more). As stated below, currency hedging is about removing the uncertainty regarding the future spot exchange rate.
Covered Interest Rate Parity
Covered Interest Rate Parity (CIRP) refers to a theoretical condition (when NFL holds) in which the relationship between interest rates and the spot and forward currency values of two countries are in equilibrium. Covered because the investor is “covered” by a forward contract: the conversion rate at time $t+1$ is known today.
E.g. say local and foreign currencies are trading at par (exchange rate = 1). However, the interest rate is lower in foreign currency. It would make sense to borrow some money in foreign currency, convert it, and then invest it in local. In doing so, one could remove uncertainty in entering a forward contract to convert back the amount later. If IRP holds, the forward rate would eradicate all the profit from the transaction.
We define:
-
$A_F$: the amount we invest in foreign currency
-
$S_0$: the spot rate i.e. the current exchange rate
-
$F$: the forward rate i.e. the future spot rate that we will use to convert the amount back
-
$r_{A,D}$: the return of the investment in domestic currency
-
$r_{A,F}$: the return of the investment in foreign currency
-
$r_D$: the interest rate in the domestic country
-
$r_F$: the interest rate in the foreign country
$r_{A,D} = \frac{\text{price of the asset (in domestic currency) at time 1}}{\text{price of the asset (in domestic currency) at time 0}}-1= \frac{A_F(1+r_{A,F})F}{A_FS_0}-1$
Covered Interest Rate Parity states that:
\[F = S_0 \frac{1+r_D}{1+r_F}\]In practice, CIRP is used for pricing: this is how banks compute the price of FX forwards.
Using this formula, we have:
\[\begin{align*} r_{A,D} &= \frac{(1+r_{A,F})}{S_0}S_0 \frac{1+r_D}{1+r_F}-1 \\ \ & = (1+r_{A,F})\frac{1+r_D}{1+r_F}-1 \end{align*}\]Which leads to:
$r_{A,D}(1+r_F) = (1+r_{A,F}) (1+r_D) - (1+r_F)$
$r_{A,D} + \color{red}{r_{A,D} r_F} = 1 + r_D + r_{A,F} + \color{red}{r_{A,F}r_D} - 1 - r_F$
We can simplify the terms in red because they are very close to zero (money market returns are usually very small). Finally:
\[r_{A,D} \approx r_{A,F} + r_D - r_F\]This result shows that money market hedging involves entering a long position in domestic currency and a short position in foreign currency. $r_D - r_F$ can be seen as the interest rate differential.
Important: as stated in this paper, currency hedging is about removing the uncertainty regarding the future spot exchange rate. It does not mean that the investor earns the local return of foreign assets; it means that he earns the local return plus an interest rate differential.
Uncovered Interest Rate Parity
In the case of Uncovered Interest Rate Parity (UIRP), the relationship is thus not about the forward rate but about expected returns: it states that the currency with the higher interest rate is expected to depreciate by the interest rate differential, so that the expected return is the same in both currencies.
The formula is the same as before, only the forward rate $F$ is replaced by the expected future spot rate $\mathbb{E}[S_1]$:
\[\mathbb{E}[S_1] = S_0 \frac{1+r_D}{1+r_F}\]In practice, UIRP is used for forecasting: it gives an expected value of the future exchange rate.
Following the same steps, we get:
\[\mathbb{E}[r_{A,D}] \approx \mathbb{E}[r_{A,F}] + r_D - r_F\]Limits: contrary to CIRP, UIRP is only a theory on expectations and it often fails in practice. A carry trade consists of borrowing in a low interest rate currency and investing in a high interest rate currency, without hedging, to earn the interest rate differential. If UIRP held, the high interest rate currency would depreciate by exactly this differential and the strategy would earn nothing on average. Since UIRP often does not hold, the depreciation is usually smaller than the differential and carry trades are profitable on average.
Additional remarks
In practice, rather than relying on UIRP, it is often more reliable to assume that the expected return of the exchange rate is zero, i.e. $\mathbb{E}[r_{FX}] = 0$. More generally, when modelling the FX component of a foreign investment, its impact is much larger on the expected risk than on the expected return: currency moves add significant volatility to the portfolio (e.g. for a foreign bond, each coupon is paid in the foreign currency and must be converted at the spot rate, so every cash flow is exposed to FX moves when computing the portfolio’s performance in domestic currency).